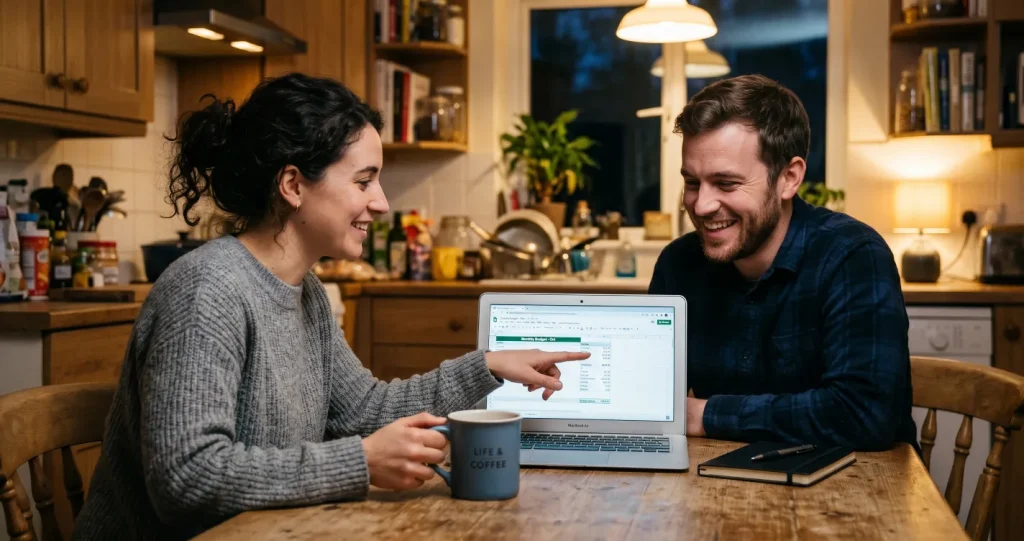

For eighteen months, Skylar and Ken built budgets. Good ones, on paper – ambitious grocery targets, aggressive restaurant cuts, clear categories. And for eighteen months, every single one collapsed within a few weeks.
They weren’t undisciplined. They were making the same mistake almost everyone makes: trying to change too much, too fast. Their eventual budget transformation didn’t come from more willpower, it came from a smaller, more honest system.
The Whiplash Cycle
Skylar had a name for it – financial whiplash. Go from spending $500 a month on groceries to a $100 target overnight, and your life rebels against the sudden restriction. Like a rubber band pulled too far, you snap back to old habits, often spending more than before out of sheer frustration.
Their restaurant spending told the same story. Before the shift, they were spending roughly $400 a week eating out – and regularly throwing away leftovers on top of it. Rather than slashing that to $100 overnight, they simply got more mindful: eating the leftovers, cooking a few more meals at home. Spending dropped naturally to $180 a week – with zero deprivation, because it happened through awareness instead of force. From there, they fine-tuned further: $180 to $160, then to $150.
The System Was the Real Problem
Here’s what most people miss about a story like this: the failures weren’t about motivation. They were about the system. Skylar and Ken’s old approach was a rearview mirror – set categories, live life, find out at month’s end whether it worked. By the time they knew something had gone wrong, it was too late to fix it.
They did have one safeguard: a low-balance alert at $200 to prevent overdrafts. But it was purely reactive. When it triggered, they had to slam the brakes across every category simultaneously – an all-or-nothing emergency stop, not a graceful correction.
What Changed: Gradual Adjustment, Weekly Reviews, Monthly Grades
The turnaround had three parts, and none of them required more willpower.
- Gradual instead of dramatic. Every adjustment moved in small steps – $180 to $160 to $150 – the same way you’d add weight gradually to build real strength, not attempt a max lift on day one.
- Responsive instead of reactive. They raised their alert threshold to $250 and added a 10-minute weekly review every Sunday – checking actual spending against plan, category by category, and adjusting the remaining days accordingly.
- Graded instead of judged. Once a month, they scored their performance like a report card. A 3 out of 10 wasn’t shame, it was information about what needed to move to a 5, then a 7. The grading session became a planning meeting, not a verdict.
Their financial advisor summed up the shift with a line worth remembering: information is like knowing you’re driving 80 miles an hour. Perspective is knowing whether you’re on the freeway or in a school zone. The number means nothing without the context of a target to measure it against.
The Before and After
Restaurant spending fell from roughly $400 a week to $150 – gradually, without a single week of feeling deprived. Their grocery target shifted from a guess ($300) to a real number they could actually sustain ($350), once they understood their true spending patterns. Their line of credit balance dropped to $526, and for the first time they could see it trending toward an actual repayment goal instead of just hoping for the best.
But the real transformation wasn’t the dollar figures. It was that budgeting stopped being a test they kept failing and became a system they adjusted every single week.
The Takeaway for Your Own Mid-Year Reset
If the last eighteen months of your financial life feels like Skylar and Ken’s – ambitious budget, quiet collapse, guilt, repeat – the fix probably isn’t a bigger goal. It’s a smaller, more honest one, paired with a weekly check-in and a monthly grade that treats a bad month as data instead of failure.
Awareness first. Then vision. Then consistent, gradual action. Then accountability that closes the loop. That’s the whole cycle – and it’s the one Skylar and Ken finally got right after 18 months of trying to skip straight to the finish line.
Not sure which financial stage you’re actually in right now? Start with the free Financial Health Assessment, it takes five minutes and shows you exactly where to focus first.
Want the complete framework behind Skylar and Ken’s turnaround, plus a real conversation about your specific numbers? Book a free consultation.
Bryan Halverson is a financial coach, the author of Be Money Strong, and the founder of BeMoneyStrong.com. He has helped hundreds of families move from Stage 1 Crisis Mode to Stage 6 Legacy Mode using the 6 Financial Stages Framework.