“What if your transmission goes tomorrow? $3,500. Can you absorb that?” When I asked Olivia and Sam that question, they answered instantly: no. That one question is where learning how to save an emergency fund really starts. Not with a savings goal, but with a clear picture of what the money is for. Here is the exact plan to build a $1,000 emergency fund in 90 days on a tight budget, plus the three decisions that keep it from vanishing.
Why 90 Days Works
Ninety days is 13 weeks. $1,000 divided by 13 is about $77 a week. For most Stage 2 households, $77 a week is uncomfortable but possible, especially when part of it comes from one-time sales instead of your paycheck. A 90-day finish line is close enough to stay motivated and long enough to build the habit.
The Week-by-Week Plan to Build an Emergency Fund Fast
Week 1: Set up the system. Open a separate high-yield savings account that isn’t linked to your everyday checking. Schedule an automatic transfer for payday, even $25. This is paying yourself first: the money leaves before you can spend it.
Weeks 2 and 3: Sell what you aren’t using. Walk through your home, garage, and closets. List the items you haven’t touched in a year. Every dollar from those sales goes straight into the fund. Most people get their fastest progress here.
Weeks 4 to 6: Redirect one expense. Pick one recurring expense you can live without for 90 days and send that exact amount to the fund. One change you keep beats ten you abandon.
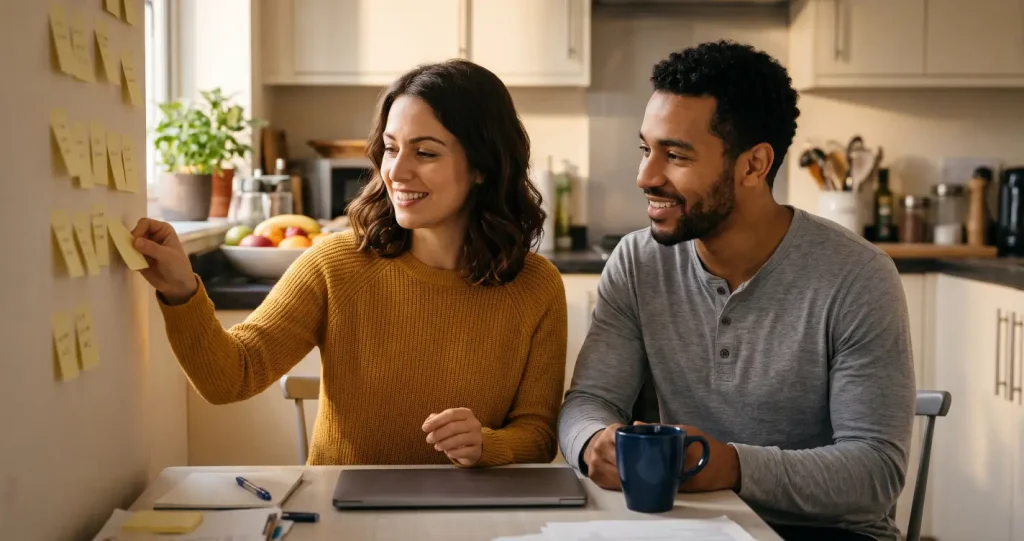
Weeks 7 to 13: Autopilot and visibility. Let the transfers run. Track your balance somewhere you see daily. Olivia and Sam pulled a post-it note off the wall for every loan they paid off; a thermometer drawing on the fridge works for your fund the same way.
Decision 1: Run the Absorption Test
Not every surprise expense belongs to your emergency fund. Before you touch it, ask: can I absorb this in this month’s budget without derailing my debt snowball?
Olivia and Sam’s annual subscriptions totaled about $356. They could technically absorb that, but it’s predictable, so it belongs in a small sinking fund. A $3,500 transmission repair fails the test immediately. That is what the emergency fund exists for.
Decision 2: Define an Emergency Before You Have One
A fund without rules gets spent on everything. Olivia and Sam wrote their definition together. An emergency is something they can’t absorb, it’s immediate and unexpected, and it affects their ability to earn or an essential: transportation, health, or housing. As Sam said, it’s “something that we wouldn’t be able to do our current lives without.”
Context matters. A small rock chip in the windshield can wait or be absorbed. A tree branch through the windshield is an emergency. Write your definition in one sentence and keep it next to your budget.
Decision 3: Write Your Order of Operations
Even a funded plan can be overwhelmed. When mold took over my home, I lived in a basement, threw away belongings, and emptied my emergency fund. I went back to ground zero. What kept me moving was a clear order: stop extra investing, use the emergency fund, take only the loan that was truly necessary, and focus on immediate needs until the crisis passed. Eight or nine years later, I’m back to paying off my house early.
Decide your order now, while you’re calm. If you have a partner, decide it together. The worst time to make financial decisions is in the middle of a crisis.
Where to Keep Your Emergency Fund
Keep it in a high-yield savings account, separate from checking and free of minimum balance requirements. Separation keeps it out of your spending flow. The interest is a bonus; the separation is the point. Some families, including mine at one point, use separate accounts for each sinking fund too. Choose the setup you’ll actually maintain.
Savings Tips for 2026: Start This Week
Open the account, set the transfer, and write your emergency definition before Friday. Then pick your first item to sell this weekend. In 90 days you’ll have $1,000 and a plan for using it, which is exactly what Tasha was missing when an $800 repair erased four months of progress.
Not sure whether your first target is $1,000 or a full three-to-six-month cushion? Take the free Financial Health Assessment. It takes about five minutes and shows you which stage you’re in.
Want help building your plan? Book a free 20-minute Discovery Call.
Bryan Halverson is a financial coach, the founder of BeMoneyStrong.com. He has helped hundreds of families move from Stage 1 Financial Crisis Mode to Stage 6 Legacy Mode using the 6 Financial Stages Framework.